How to Optimize Your Ultimate Rewards Credit for Maximum Value
The Ultimate Rewards program isn’t just another credit card perk—it’s a sophisticated financial tool that, when mastered, can transform everyday spending into high-value travel, statement credits, or even cash back. Unlike generic cashback programs, managing your Ultimate Rewards credit requires precision: aligning spending with earning rates, strategizing redemptions for peak value, and navigating the program’s evolving rules. The difference between a casual user and a power optimizer isn’t luck; it’s methodical execution.
Consider this: a traveler who blindly books flights and hotels without leveraging Ultimate Rewards credit might pay full fare, while a savvy user could cover the same trip with points—often at a fraction of the cost. The gap isn’t just financial; it’s about control. Points are liquid assets, exchangeable for flights, luxury stays, or even Amazon gift cards, but their value hinges on how you earn, store, and deploy them. The program’s flexibility is its superpower, but only if you understand its mechanics.
Missteps are costly. Overlooking annual fees, missing redemption deadlines, or failing to stack categories can leave thousands of points on the table. The best optimizers treat Ultimate Rewards credit like a high-yield investment account—one where every dollar spent is a calculated move toward a bigger payoff. This isn’t about chasing rewards for their own sake; it’s about turning routine expenses into strategic advantages.
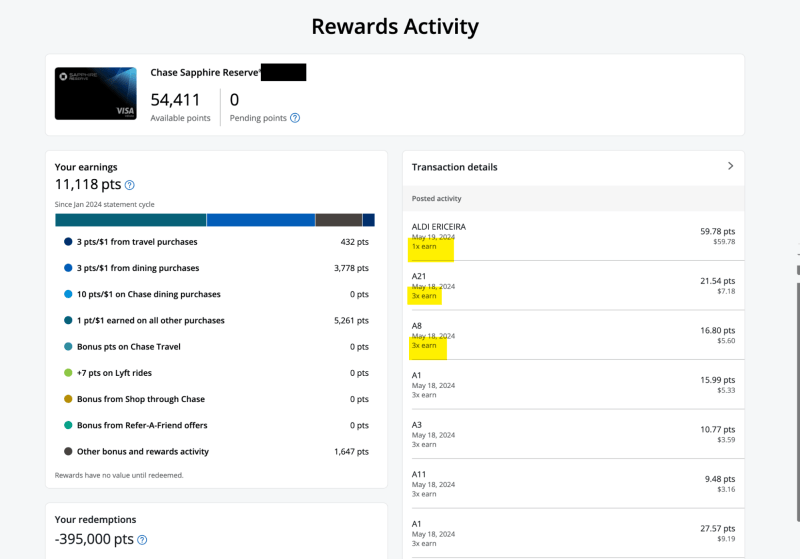
The Complete Overview of Managing Your Ultimate Rewards Credit
Ultimate Rewards credit is the backbone of Chase’s travel rewards ecosystem, offering a blend of flexibility and exclusivity that few loyalty programs match. At its core, the system operates on a points-based model where spending across Chase credit cards earns rewards that can be redeemed for travel, merchandise, or cash back. The program’s strength lies in its tiered structure: basic earners, premium cardholders (like Sapphire or Ink), and elite status members (e.g., Chase Sapphire Reserve members) all access different redemption rates, transfer partners, and perks. What sets it apart is the ability to transfer points to airline and hotel partners at a 1:1 ratio, often unlocking premium cabin upgrades or elite status—something cash redemptions can’t replicate.
Yet, the program’s complexity is its double-edged sword. New users often underestimate the importance of card selection, assuming all Chase cards offer the same value. In reality, the Chase Sapphire Preferred® Card (60,000-point sign-up bonus) and the Chase Sapphire Reserve® Card (50,000-point bonus) cater to distinct spending habits and redemption goals. The former excels for everyday travelers; the latter is tailored for luxury seekers who prioritize premium travel benefits. Managing your Ultimate Rewards credit effectively means aligning your lifestyle with the right card—and then leveraging its features to maximize returns.
Historical Background and Evolution
Ultimate Rewards traces its origins to 2009, when Chase launched the program as a consolidation of its existing loyalty initiatives. The goal was simple: create a unified system where customers could earn and redeem rewards across multiple Chase cards, eliminating the fragmentation of separate programs. Early iterations were basic, offering 1-2% cash back or fixed redemption rates for travel. But the real turning point came in 2016 with the introduction of the Chase Sapphire Reserve, which introduced a 3x points bonus on travel and dining, along with a $300 annual travel credit. This shift signaled Chase’s pivot toward premiumization, positioning Ultimate Rewards as a tool for high-net-worth travelers.
Table of Contents
- The Complete Overview of Managing Your Ultimate Rewards Credit
- Historical Background and Evolution
- Core Mechanics: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can I combine Ultimate Rewards credit from multiple Chase cards?
- Q: Are there blackout dates for travel redemptions?
- Q: How do I maximize the value of my Ultimate Rewards credit?
- Q: Can I use Ultimate Rewards credit for international travel?
- Q: What happens if I don’t use my Ultimate Rewards credit before it expires?
- Q: Are there any hidden fees when managing my Ultimate Rewards credit?
The program’s evolution hasn’t been linear. Regulatory pressures, like the 2019 crackdown on sign-up bonuses, forced Chase to adjust its strategy—temporarily reducing bonus thresholds before reintroducing them in modified forms. Meanwhile, the addition of transfer partners (e.g., United, Hyatt, British Airways) expanded redemption options beyond Chase’s own travel portal. Today, managing your Ultimate Rewards credit involves navigating a landscape shaped by both Chase’s internal policies and external market forces, such as fluctuating airline fuel surcharges or hotel loyalty devaluations. The program’s adaptability has kept it relevant, but it demands constant vigilance from users.
Core Mechanics: How It Works
At its simplest, Ultimate Rewards credit is earned by spending on eligible Chase cards. Points accrue at varying rates depending on the card and category: 1x for most purchases, 2x on travel/dining (Sapphire Preferred), or 3x on travel/dining/entertainment (Reserve). The system also includes bonus categories that rotate annually (e.g., streaming services, gas stations), adding layers of earning potential. What’s often overlooked is the role of the Ultimate Rewards portal itself—a centralized hub where users can view balances, transfer points to partners, or book travel directly. This portal is where the magic happens: redeeming 50,000 points for a $750 travel credit (via the Reserve’s annual travel credit) or transferring 50,000 points to United for a round-trip business class ticket.
The devil is in the details. For instance, the Chase Freedom Flex® card earns 5% cash back in rotating categories—but those points can be converted to Ultimate Rewards at a 1:1 ratio, effectively turning a cashback card into a travel rewards powerhouse. Similarly, the Chase Freedom Unlimited® card offers 1.5% cash back on all purchases, which can also be transferred to Ultimate Rewards. The key is recognizing that managing your Ultimate Rewards credit isn’t limited to premium cards; even entry-level cards can feed into the system. However, the real value emerges when you combine multiple cards to cover all spending categories, a strategy known as "card stacking."
Key Benefits and Crucial Impact
Ultimate Rewards credit isn’t just about earning points—it’s about unlocking experiences that cash can’t buy. The program’s ability to transfer points to airline and hotel partners at a fixed rate (1:1) means you’re often getting better value than booking directly. For example, transferring 60,000 points to United for a round-trip economy ticket might cost less than purchasing the same flight with cash. Beyond travel, the program’s flexibility extends to statement credits, gift cards, and even charitable donations, making it a versatile tool for financial optimization. The psychological benefit is equally significant: knowing you’re earning rewards on every purchase can alter spending habits, encouraging discipline in areas like dining or groceries.
Yet, the program’s impact isn’t just personal—it’s systemic. By incentivizing travel and luxury spending, Ultimate Rewards indirectly supports industries like hospitality and aviation. For frequent travelers, the program can offset the cost of business trips, turning a necessary expense into a tax-advantaged benefit. Even for leisure travelers, the ability to redeem points for premium cabins or resort stays can transform a vacation into a first-class experience. The catch? Success depends on understanding the program’s nuances, from transfer partner valuations to the optimal timing for redemptions.
"Ultimate Rewards credit is like a financial Swiss Army knife—it cuts through the noise of generic cashback programs by offering targeted rewards that align with real-world spending. The difference between a mediocre user and a master is knowing when to deploy each tool."
— Industry Analyst, Travel Rewards Forum
Major Advantages
- Flexibility in Redemption: Points can be used for travel bookings, statement credits, gift cards, or even transferred to airline/hotel partners—no blackout dates or restrictions on most redemptions.
- High-Value Transfer Partners: Airlines like United and British Airways, along with hotel chains like Hyatt, offer elite status or premium cabin upgrades when points are transferred, often at a higher value than direct redemptions.
- Annual Travel Credits: Cards like the Sapphire Reserve include a $300 travel credit, effectively reducing out-of-pocket costs for flights or hotels.
- No Foreign Transaction Fees: Many Ultimate Rewards cards (e.g., Sapphire Reserve) waive fees on international purchases, making them ideal for global travelers.
- Bonus Categories and Stacking: Rotating categories (e.g., Amazon Prime, gas stations) and the ability to combine multiple cards (e.g., Freedom Flex + Sapphire Preferred) maximize earning potential.

Comparative Analysis
| Feature | Ultimate Rewards | American Express Membership Rewards |
|---|---|---|
| Transfer Partners | United, Hyatt, British Airways, Marriott (via Chase portal) | Delta, Hilton, Singapore Airlines, ANA (via Amex portal) |
| Redemption Flexibility | Travel bookings, statement credits, gift cards, transfers | Travel bookings, statement credits, gift cards, transfers |
| Annual Fees | $95 (Sapphire Preferred), $550 (Sapphire Reserve) | $95 (Gold), $695 (Platinum) |
| Sign-Up Bonuses | Up to 60,000 points (Sapphire Preferred) | Up to 150,000 points (Platinum) |
Future Trends and Innovations
The next phase of Ultimate Rewards credit will likely focus on personalization and integration with emerging technologies. As AI-driven spending analytics become more sophisticated, Chase may introduce dynamic earning rates—adjusting rewards based on real-time spending patterns or market conditions. Imagine a system where your points earn at 4x for a limited-time category because Chase detects you’re a frequent diner in a high-value neighborhood. Similarly, blockchain-based loyalty programs could enable seamless point transfers between partners, reducing friction in redemptions. The program’s future may also see deeper partnerships with fintech platforms, allowing users to earn Ultimate Rewards credit on non-Chase transactions (e.g., Venmo, PayPal).
Regulatory changes will also shape the landscape. With stricter bonus restrictions and potential caps on point valuations, managing your Ultimate Rewards credit will require even greater adaptability. However, the program’s resilience suggests it will continue evolving—whether through expanded transfer partners, enhanced travel benefits, or innovative redemption options. The key for users will be staying ahead of these shifts, treating Ultimate Rewards not as a static tool but as a dynamic asset that demands proactive management.

Conclusion
Managing your Ultimate Rewards credit isn’t about chasing the highest sign-up bonus or the flashiest travel perk—it’s about building a system that works for your spending habits and financial goals. The most successful users treat the program as a long-term strategy, not a short-term hack. Whether you’re a business traveler, a leisure explorer, or a savvy shopper, the program’s potential is unlocked through discipline: choosing the right cards, optimizing redemptions, and staying informed about changes. The rewards aren’t just in the points; they’re in the freedom to travel, dine, or invest without the constraints of cash.
As the program evolves, so too must your approach. What worked last year—like transferring points to a specific airline—may not be optimal this year due to devaluations or new partners. The best optimizers don’t just earn points; they earn intelligence. By mastering the mechanics, leveraging transfer partners, and adapting to trends, you turn Ultimate Rewards credit into a force multiplier for your lifestyle. The question isn’t whether you can afford to use the program—it’s whether you can afford not to.
Comprehensive FAQs
Q: Can I combine Ultimate Rewards credit from multiple Chase cards?
A: Yes. All Ultimate Rewards points earned across Chase cards (e.g., Sapphire Preferred, Freedom Flex) are pooled into a single account. This allows you to stack cards to cover all spending categories—for example, using the Freedom Flex for rotating categories and the Sapphire Preferred for travel/dining.
Q: Are there blackout dates for travel redemptions?
A: Most Ultimate Rewards travel redemptions (via the Chase portal) have no blackout dates, but airline/hotel transfers may be subject to partner restrictions. Always check the specific terms when transferring points to a third-party loyalty program.
Q: How do I maximize the value of my Ultimate Rewards credit?
A: Focus on high-value redemptions: transferring points to airline partners for premium cabins, using the Sapphire Reserve’s annual travel credit for statement credits, or booking luxury hotels via the Chase portal. Avoid cash redemptions unless the value is clearly superior.
Q: Can I use Ultimate Rewards credit for international travel?
A: Yes, but ensure your card has no foreign transaction fees (e.g., Sapphire Reserve). Points can be used for international flights, hotels, or even foreign gift cards. However, transfer partners may have their own restrictions.
Q: What happens if I don’t use my Ultimate Rewards credit before it expires?
A: Ultimate Rewards points do not expire as long as your account remains active. However, some transfer partners (e.g., airline loyalty programs) may have their own expiration policies, so monitor those separately.
Q: Are there any hidden fees when managing my Ultimate Rewards credit?
A: The primary fees are annual card charges (e.g., $95 for Sapphire Preferred). However, third-party transfer partners may impose their own fees (e.g., airline change fees). Always review terms before redeeming.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Filmfestivalcircuit.