The Hidden Complexity Behind Bill Every Payment Method Explained
Payment systems are the unseen arteries of commerce, yet few understand how they actually bill every payment method—let alone the nuanced differences between a credit card swipe and a blockchain transaction. The process isn’t just about swiping or tapping; it’s a layered ecosystem where routing, fraud detection, and currency conversion collide. Take the example of a $50 coffee purchase: the merchant’s terminal doesn’t just deduct funds—it triggers a cascade of authorization requests, clearing cycles, and settlement protocols, each with its own cost structure and risk profile. What’s less discussed is how these methods diverge when processing recurring bills, international transfers, or microtransactions, where fees can silently eat into profitability.
The gap between consumer convenience and operational complexity widens when examining bill every payment method explained in practice. A direct debit might seem seamless to the end user, but behind the scenes, it involves bank-to-bank reconciliation, mandate validations, and failed-transaction retries that merchants rarely disclose. Meanwhile, digital wallets like Apple Pay or Alipay abstract away the underlying rails—yet their success hinges on partnerships with acquirers, processors, and even governments, each imposing their own rules on transaction limits, chargebacks, and data retention. The result? A fragmented landscape where the "best" payment method depends on whether you’re a street vendor in Lagos, a SaaS subscription service in Berlin, or a cross-border e-commerce giant.
This disconnect isn’t accidental. Payment providers deliberately obfuscate the mechanics of how bills are settled across different methods to maintain pricing power and loyalty. A merchant accepting Visa might assume a flat 2.9% fee, but that masks dynamic interchange rates, assessment fees, and currency conversion markups when processing euros or yen. The same ambiguity applies to alternative methods: Does a BNPL (buy now, pay later) service like Klarna bill every payment method the same way as a traditional credit card? The answer lies in the fine print—where deferred interest, late fees, and merchant discounts create a secondary economy of financial incentives.

The Complete Overview of Bill Processing Across Payment Methods
The term bill every payment method explained encompasses far more than the act of charging a customer. It refers to the end-to-end lifecycle of a transaction, from initiation to final settlement, where each payment type—cash, card, digital, or even barter—follows distinct technical and regulatory pathways. At its core, billing involves three critical phases: authorization (verifying funds), capture (reserving funds), and settlement (funds moving between accounts). The method chosen dictates not only the speed of these phases but also the visibility of fees, the risk of fraud, and the ability to reverse transactions. For instance, a card payment’s authorization window is typically 24–48 hours, during which the merchant holds a provisional credit—whereas a cryptocurrency transaction on Lightning Network settles in milliseconds but lacks the same chargeback protections.
What unifies these disparate systems is the role of intermediaries. No payment is truly "peer-to-peer" without a network of banks, processors, and acquirers facilitating the transfer. Even cash—often perceived as the simplest bill every payment method—relies on a complex web of ATMs, deposit reconciliation, and anti-money-laundering (AML) checks before it can be used to settle a bill. The digital revolution has only accelerated this complexity: contactless cards, mobile wallets, and central bank digital currencies (CBDCs) each introduce new layers of encryption, biometric authentication, and real-time clearing. Yet, despite these advancements, the fundamental question remains: How do these systems ensure that a bill—whether for a utility, subscription, or retail purchase—is accurately recorded, securely processed, and fairly allocated between parties?
Historical Background and Evolution
The evolution of bill every payment method explained mirrors the broader history of financial infrastructure. The first recorded bills date back to ancient Mesopotamia, where clay tablets documented grain exchanges—but the concept of systematic billing emerged with the rise of double-entry bookkeeping in 15th-century Italy. Fast forward to the 19th century, and the advent of paper checks and telegraph-based transfers laid the groundwork for modern payment rails. However, it wasn’t until the 1970s that electronic payment networks, like Visa’s global system, began standardizing the process of how bills are settled across different methods. This era also saw the birth of credit card networks, which introduced interchange fees—a revenue model that remains contentious today.
Table of Contents
- The Complete Overview of Bill Processing Across Payment Methods
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How do interchange fees affect the cost of processing a bill via credit card?
- Q: Can I use cryptocurrency to pay bills like utilities or rent?
- Q: Why do some digital wallets (e.g., PayPal) charge higher fees than others (e.g., Venmo) for the same transaction?
- Q: How does chargeback fraud impact the ability to bill customers via cards?
- Q: What’s the difference between settlement and clearing in payment processing?
The 21st century has been defined by digital disruption, with the rise of open banking, fintech, and decentralized ledgers challenging traditional billing models. The introduction of ISO 20022 in 2004, a global messaging standard for financial transactions, allowed for richer data exchange, enabling methods like SEPA in Europe to process cross-border bills with near-instant settlement. Meanwhile, the 2008 financial crisis accelerated the adoption of real-time payment systems (RTP), such as FedNow in the U.S. and Faster Payments in the UK, which now handle billions in bill-related transactions annually. The most recent shift? The integration of artificial intelligence into fraud detection and dynamic pricing, where payment methods are no longer static but adapt in real time to risk profiles and market conditions.
Core Mechanisms: How It Works
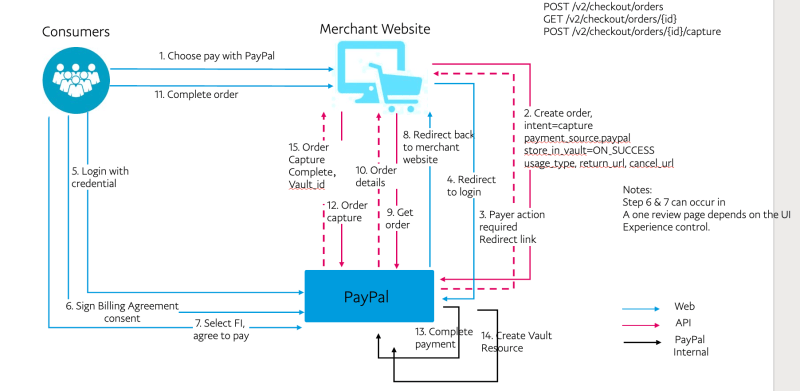
At the technical level, bill every payment method explained involves a sequence of protocols that vary by network. For card payments, the process begins with the merchant’s point-of-sale (POS) system sending an authorization request to the acquirer, who routes it through a payment processor (e.g., Stripe, Adyen) to the card network (Visa, Mastercard). The issuer bank then verifies the cardholder’s funds and either approves or declines the transaction. Once approved, the merchant captures the funds, and the acquirer settles the net amount (after fees) into the merchant’s account—typically within 2–3 business days. In contrast, digital wallets like PayPal or WeChat Pay bypass traditional card rails by using proprietary settlement networks, often with same-day funding for a premium.
Alternative methods introduce further variations. ACH (Automated Clearing House) transfers, used for direct debits and payroll, operate on a batch-processing model where transactions are grouped and settled in cycles (e.g., every 24 hours). This delays finality but reduces costs, making it ideal for recurring bills like subscriptions. Cryptocurrencies, meanwhile, leverage blockchain consensus mechanisms—Proof of Work (e.g., Bitcoin) or Proof of Stake (e.g., Ethereum)—to validate transactions without intermediaries. However, their volatility and lack of chargeback protections make them less suitable for high-value billing scenarios unless paired with stablecoins or payment wrappers like Lightning Network. The key takeaway? The mechanics of how bills are processed are not just about technology but also about trust, speed, and the economic incentives of each participant.
Key Benefits and Crucial Impact
The ability to efficiently bill every payment method is the backbone of modern commerce, enabling everything from microtransactions to billion-dollar B2B settlements. For consumers, it translates to convenience—whether it’s the tap of a contactless card or the one-click checkout of a saved digital wallet. For businesses, the right payment method can mean the difference between profitability and loss, especially when factoring in fees, chargeback rates, and international conversion costs. The impact extends beyond finance: governments use billing systems to collect taxes, utilities rely on them for meter readings, and even charitable donations now flow through optimized payment rails. Yet, the benefits are not without trade-offs. The same systems that enable seamless transactions also create vulnerabilities—fraud, data breaches, and regulatory compliance burdens that grow with each new method.
Understanding how bills are settled across different methods is particularly critical for merchants operating in multiple regions. A café in Tokyo accepting Alipay might enjoy lower fees than one using Visa, but the latter offers global acceptance. Similarly, a SaaS company billing customers in Argentina must navigate currency controls and inflation-adjusted pricing, which traditional card networks may not support. The stakes are highest for cross-border transactions, where FX markups and correspondent bank fees can add 5–10% to the cost of processing a single bill. The solution? Many businesses now use multi-acquirer platforms that dynamically route transactions to the cheapest or fastest method, effectively "bill every payment method" in a way that maximizes efficiency.
"The future of payments isn’t about choosing one method over another—it’s about orchestrating them in a way that aligns with the transaction’s risk, speed, and cost profile."
— David Marcus, Former Head of Payments at Facebook (now Meta)
Major Advantages
- Speed and Liquidity: Real-time payment methods (e.g., RTP, CBDCs) eliminate the 2–5 day settlement lag of traditional cards, critical for time-sensitive bills like event tickets or perishable goods.
- Cost Efficiency: Digital wallets and ACH reduce interchange fees compared to credit cards, making them ideal for high-volume, low-value transactions (e.g., public transport, vending machines).
- Global Reach: Methods like Wise (formerly TransferWise) or cryptocurrencies enable cross-border billing without intermediaries, bypassing correspondent bank fees.
- Fraud Mitigation: Tokenization (e.g., Apple Pay) and biometric authentication reduce card-not-present fraud, a growing pain point for e-commerce.
- Data Insights: Modern payment processors provide granular transaction data, allowing businesses to optimize pricing, detect anomalies, and personalize billing cycles.
Comparative Analysis
| Payment Method | Key Features vs. Billing |
|---|---|
| Credit/Debit Cards |
|
| Digital Wallets (PayPal, Alipay) |
|
| ACH (Direct Debit) |
|
| Cryptocurrencies |
|
Future Trends and Innovations
The next decade of bill every payment method explained will be shaped by three converging forces: regulatory pressure, technological innovation, and shifting consumer behaviors. On the regulatory front, governments are tightening controls on cross-border payments (e.g., EU’s Payment Services Directive 3) and mandating stronger fraud prevention (e.g., Strong Customer Authentication). This will force payment providers to adopt more transparent billing practices, reducing hidden fees and improving dispute resolution. Technologically, the rise of CBDCs (central bank digital currencies) and atomized money (e.g., microtransactions via stablecoins) will enable bills to be processed in fractions of a cent, unlocking new use cases like pay-per-use services or dynamic pricing models. Meanwhile, AI-driven dynamic routing—where a single transaction is split across multiple payment methods to optimize costs—will become standard for large enterprises.
Consumer expectations will also redefine how bills are settled across different methods. Gen Z’s preference for "invisible" payments (e.g., embedded finance, social commerce) will push platforms like TikTok Shop or Shopify to integrate seamless billing into non-traditional interfaces. Similarly, the demand for "green" payments—where carbon footprints are factored into transaction costs—will incentivize processors to adopt sustainable settlement networks. The most disruptive trend? The blurring of lines between payments and other financial services. Today’s bill payment might tomorrow include instant loans, micro-investments, or even NFT-based loyalty rewards—all processed within the same transaction flow. The challenge for businesses will be navigating this complexity while ensuring that the bill every payment method remains secure, compliant, and customer-centric.

Conclusion
The landscape of bill every payment method explained is no longer a static set of options but a dynamic ecosystem where technology, regulation, and economics collide. What was once a choice between cash and check has expanded into a menu of 50+ methods, each with its own trade-offs in cost, speed, and security. The key to success lies in understanding not just the surface-level differences (e.g., "tap vs. swipe") but the underlying mechanics—how authorization works, where fees are hidden, and what happens when a transaction fails. For merchants, this means adopting agile payment stacks that can pivot between methods based on geography, customer preference, and risk. For consumers, it’s about demanding transparency in a system that increasingly treats billing as a black box.
As we move toward a cashless future, the question is no longer which payment method to use but how to integrate them strategically. The businesses that thrive will be those that treat payment methods as tools—not as endpoints—but that requires a deep dive into the often-overlooked details of how bills are actually processed. The systems are complex, but the rewards—efficiency, security, and scalability—are worth the effort to master them.
Comprehensive FAQs
Q: How do interchange fees affect the cost of processing a bill via credit card?
Interchange fees are a percentage (typically 1.5–3.5%) plus a fixed amount ($0.10–$0.30) that merchants pay to card networks (Visa, Mastercard) and issuers for each transaction. These fees are non-negotiable for most small businesses but can be reduced through contracts with high-volume processors or by accepting debit cards (which often have lower interchange rates). For example, a $100 bill processed via Visa Signature might incur ~$3.20 in fees, while the same bill on a corporate Amex could cost ~$2.80. The fees are baked into the merchant’s pricing or absorbed as profit margin.
Q: Can I use cryptocurrency to pay bills like utilities or rent?
While cryptocurrencies are increasingly accepted by forward-thinking businesses, traditional billers (utilities, landlords, governments) rarely support them due to volatility, regulatory hurdles, and the lack of chargeback protections. However, workarounds exist: some property management companies accept Bitcoin via third-party processors (e.g., BitPay), and utilities in crypto-friendly regions (e.g., Switzerland, Puerto Rico) may offer payment wrappers. For rent, tenants might use stablecoins (e.g., USDC) to avoid price swings, but landlords typically require fiat conversion, adding fees. Always confirm with the provider before attempting a crypto bill payment.
Q: Why do some digital wallets (e.g., PayPal) charge higher fees than others (e.g., Venmo) for the same transaction?
Fees vary based on the wallet’s business model, regional pricing, and transaction volume. PayPal, for instance, charges 2.9% + $0.30 for most transactions but offers lower rates for its premium business accounts or in markets like Germany (where fees are capped at 1.9%). Venmo, owned by PayPal, often shows $0 fees for personal transfers but charges merchants ~3% for goods/services. The discrepancy stems from PayPal’s dual role as both a consumer payment app and a merchant processor—it cross-subsidizes personal users by charging more to businesses. Additionally, wallets in high-fee regions (e.g., Latin America) may absorb costs to remain competitive.
Q: How does chargeback fraud impact the ability to bill customers via cards?
Chargeback fraud—a malicious dispute filed by a cardholder—directly erodes merchant revenue. When a chargeback occurs, the merchant loses the sale amount plus the original interchange fee, and may face penalties from the card network (e.g., Visa’s "chargeback monitoring program"). High fraud rates can lead to account termination or increased fees. To mitigate this, merchants use tools like 3D Secure (SCA), velocity checks, and AI fraud detection. For example, a $500 bill processed via a high-risk card (e.g., prepaid, virtual) might trigger additional authentication steps. The key is balancing security with friction—too many checks can deter legitimate customers, while too few invite fraudsters.
Q: What’s the difference between settlement and clearing in payment processing?
Clearing is the behind-the-scenes process of verifying and batching transactions between banks and payment networks. It ensures that both the merchant and cardholder have sufficient funds before the transaction is approved. Settlement, on the other hand, is the actual transfer of funds from the customer’s bank to the merchant’s account, which typically occurs 1–3 days later (for cards) or same-day (for real-time methods like RTP). For example, when you pay a $20 bill with a debit card, clearing happens instantly (the bank checks your balance), but settlement takes 1–2 days (the merchant receives the funds). ACH and wire transfers skip the clearing step, settling directly but with stricter fund availability rules.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Filmfestivalcircuit.