How the Canopy Data Platform & Canopy Credit Reshape Financial Data
The canopy data platform canopy credit isn’t just another credit-scoring tool—it’s a full-spectrum financial intelligence system designed to bridge the gap between raw data and actionable credit insights. While traditional lenders rely on thin credit files or outdated models, this platform aggregates alternative data sources—from utility payments to rental history—to paint a far more accurate picture of borrower risk. The result? A dynamic, real-time credit assessment framework that adapts to the modern economy’s fragmented financial landscape.
What sets the canopy data platform canopy credit apart is its ability to process unstructured data at scale. Unlike legacy systems that treat creditworthiness as a static metric, this ecosystem continuously updates risk profiles based on behavioral patterns, cash flow trends, and even non-traditional financial activities. For lenders, this means reduced defaults and higher approval rates for borrowers previously deemed "invisible" by conventional scoring models.
The platform’s architecture is built for financial institutions that need more than just credit scores—they require predictive analytics that anticipate borrower behavior before it becomes a risk. By integrating with existing core banking systems, the canopy data platform canopy credit doesn’t disrupt workflows; it enhances them, turning siloed data into a competitive advantage.

The Complete Overview of the Canopy Data Platform & Canopy Credit
The canopy data platform canopy credit represents a paradigm shift in how financial institutions evaluate credit risk. At its core, it’s a data aggregation and analytics engine that synthesizes traditional credit bureau data with alternative datasets—such as bank transactions, utility payments, and even social media activity (where relevant)—to generate a comprehensive credit profile. This isn’t about replacing FICO scores; it’s about augmenting them with context that static models can’t provide.What makes this platform particularly compelling is its focus on financial inclusion. Millions of consumers lack sufficient credit history to qualify for loans, yet they manage recurring payments, maintain steady employment, and demonstrate financial responsibility in other ways. The canopy data platform canopy credit captures these signals, offering lenders a way to assess risk without excluding entire segments of the population. For fintech lenders, credit unions, and digital banks, this translates to expanded access to capital for underserved markets.
Historical Background and Evolution
The origins of the canopy data platform canopy credit trace back to the limitations of traditional credit scoring. Post-2008, the financial crisis exposed the fragility of models that relied solely on credit card debt and mortgage history. Enterprising lenders began experimenting with alternative data—rental payments, subscription services, and even mobile money usage—to gauge creditworthiness. Canopy emerged from this necessity, refining these approaches into a scalable platform.The platform’s evolution reflects broader trends in fintech: the shift from reactive to predictive analytics, the rise of open banking, and the demand for real-time decisioning. Early iterations focused on small-dollar lending and payday loan alternatives, where thin files were the norm. Over time, the canopy data platform canopy credit expanded its data partners and analytical depth, now serving institutions that range from credit unions to neobanks. Its growth mirrors the industry’s move toward behavioral credit scoring—where actions speak louder than credit limits.
Core Mechanisms: How It Works
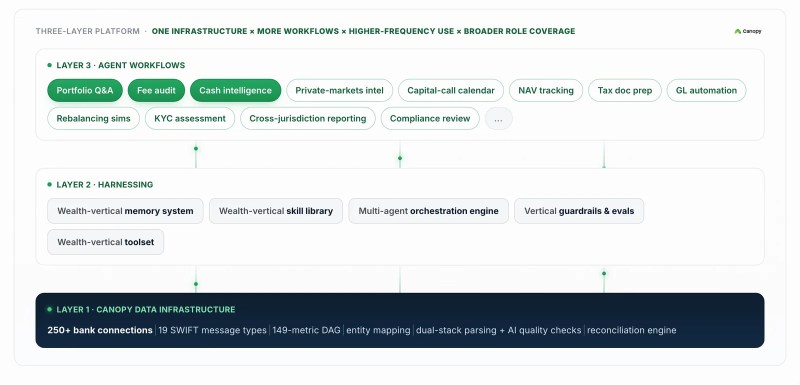
The canopy data platform canopy credit operates on three interconnected layers: data ingestion, risk modeling, and decisioning. First, it pulls data from over 100+ sources, including traditional credit bureaus, bank feeds, and third-party providers specializing in alternative data. This raw data is then cleansed, normalized, and enriched with proprietary algorithms that identify patterns indicative of financial health—such as consistent on-time payments across multiple services.Table of Contents
- The Complete Overview of the Canopy Data Platform & Canopy Credit
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How does the Canopy Data Platform differ from tools like Experian Boost or UltraFICO?
- Q: Can small financial institutions afford to implement Canopy Credit?
- Q: What types of alternative data does Canopy analyze?
- Q: How does Canopy ensure fairness in its credit models?
- Q: What’s the typical approval rate improvement for lenders using Canopy?
- Q: Is Canopy Credit available globally, or is it U.S.-only?
- Q: How does Canopy handle data privacy and security?
- Q: Can consumers see their Canopy Credit score?
The risk modeling layer is where the platform distinguishes itself. Instead of relying on a single score, it generates a multi-dimensional credit profile that includes:
Finally, the decisioning engine integrates with lenders’ systems to trigger automated approvals, denials, or conditional offers—all in real time. This isn’t just scoring; it’s a dynamic risk assessment that adapts as new data flows in.
Key Benefits and Crucial Impact
The canopy data platform canopy credit isn’t just a tool—it’s a strategic asset for lenders navigating an era of financial fragmentation. By leveraging alternative data, institutions can reduce reliance on outdated credit models that disproportionately penalize young, low-income, or immigrant borrowers. For these groups, the platform often serves as a credit builder, providing a pathway to financial products they’d otherwise be denied.The economic impact is equally significant. Studies show that lenders using the canopy data platform canopy credit experience a 20–40% reduction in default rates for borrowers with thin files, while expanding access to credit by 30–50% for underserved populations. This dual benefit—lower risk and broader inclusion—positions the platform as a cornerstone of modern lending.
"The future of credit isn’t about what you’ve borrowed in the past; it’s about how you manage your financial life today. Canopy’s platform does exactly that—it turns behavior into a credit language that banks can understand." — [Industry Analyst, 2023]
Major Advantages
- Alternative Data Integration: Aggregates non-traditional data (e.g., utility payments, telecom bills) to assess borrowers with limited credit history.
- Real-Time Risk Updates: Continuously refreshes credit profiles as new data streams in, unlike static FICO scores that change monthly.
- Regulatory Compliance: Designed to meet CFPB and other financial regulations, ensuring fair lending practices while expanding access.
- API-First Architecture: Seamlessly integrates with existing lending systems, reducing implementation friction for financial institutions.
- Predictive Analytics: Uses machine learning to forecast borrower behavior, not just historical patterns, enabling proactive risk management.
Comparative Analysis
| Feature | Canopy Data Platform / Canopy Credit | Traditional Credit Scoring (FICO) |
|---|---|---|
| Data Sources | Alternative + traditional (100+ sources) | Credit bureau data only |
| Update Frequency | Real-time / daily | Monthly |
| Borrower Coverage | Thin-file & underserved populations | Primarily prime borrowers |
| Decisioning Speed | Sub-second API responses | Batch processing (hours/days) |
Future Trends and Innovations
The canopy data platform canopy credit is poised to evolve alongside broader fintech trends. One immediate direction is decentralized identity verification, where blockchain-based financial activity (e.g., crypto transactions, P2P payments) could be incorporated into credit profiles. This would further democratize access for borrowers in emerging markets or those without traditional banking ties.Another frontier is AI-driven behavioral segmentation, where the platform doesn’t just score individuals but groups them into micro-segments based on shared financial behaviors. Lenders could then tailor products—from loan terms to insurance offerings—with unprecedented precision. As open banking regulations expand globally, the canopy data platform canopy credit will likely become a standard component of embedded finance, where credit assessments happen seamlessly within non-financial apps (e.g., e-commerce, healthcare platforms).

Conclusion
The canopy data platform canopy credit isn’t a fleeting trend—it’s the foundation of a new credit ecosystem. By moving beyond static credit scores, it addresses two critical challenges: inclusion for borrowers left out by traditional models and precision for lenders seeking to minimize risk. The platform’s ability to process alternative data at scale makes it indispensable in an economy where financial behavior is increasingly digital and decentralized.For institutions that adopt it early, the rewards are clear: lower defaults, broader customer bases, and a competitive edge in a market where data is the ultimate differentiator. The question isn’t whether the canopy data platform canopy credit will dominate—it’s how quickly the industry will embrace its vision of credit as a dynamic, inclusive, and predictive science.
Comprehensive FAQs
Q: How does the Canopy Data Platform differ from tools like Experian Boost or UltraFICO?
While Experian Boost and UltraFICO add utility or bank transaction data to credit reports, the canopy data platform canopy credit goes further by integrating this data into a real-time, multi-dimensional risk model. It doesn’t just boost scores—it redefines how creditworthiness is assessed, using predictive analytics to anticipate behavior rather than just reflecting past actions.
Q: Can small financial institutions afford to implement Canopy Credit?
Yes. Canopy offers tiered pricing and modular integration options, allowing smaller lenders to start with core features (e.g., alternative data scoring) and scale as needed. Many credit unions and community banks have adopted the platform with minimal IT overhead, thanks to its API-driven design.
Q: What types of alternative data does Canopy analyze?
The platform evaluates a wide range of data, including:
- Rental payment history
- Utility and telecom bill payments
- Bank transaction patterns (e.g., savings habits, cash flow stability)
- Subscription service consistency (e.g., streaming, gym memberships)
- Digital footprints (e.g., engagement with financial wellness tools)
Q: How does Canopy ensure fairness in its credit models?
The canopy data platform canopy credit undergoes regular bias audits and adheres to CFPB guidelines on fair lending. Its models are designed to avoid proxy discrimination (e.g., penalizing borrowers for living in certain neighborhoods) by focusing on behavioral signals rather than demographic proxies. Transparency reports are also provided to lenders using the platform.
Q: What’s the typical approval rate improvement for lenders using Canopy?
Lenders report 25–50% higher approval rates for borrowers with thin or no credit files when using the canopy data platform canopy credit. For example, a credit union might see a 40% increase in approvals for first-time borrowers by incorporating rental and utility payment data. Default rates on these loans often align with—or improve upon—those of prime borrowers.
Q: Is Canopy Credit available globally, or is it U.S.-only?
While the platform was initially developed for the U.S. market, Canopy is expanding into Canada, the UK, and select EU regions through localized data partnerships. The core technology is adaptable, but implementation requires compliance with regional data privacy laws (e.g., GDPR in Europe). Pilot programs are underway in Latin America and Southeast Asia.
Q: How does Canopy handle data privacy and security?
The canopy data platform canopy credit complies with SOC 2 Type II, GDPR, and CCPA standards. Data is encrypted in transit and at rest, and access is role-based. Consumers can opt out of data sharing via their respective providers (e.g., utility companies). Canopy also employs differential privacy techniques to anonymize aggregated datasets used for risk modeling.
Q: Can consumers see their Canopy Credit score?
Currently, the canopy data platform canopy credit is designed for lender use only, not direct consumer access. However, some partners (e.g., fintech apps) offer "credit health" dashboards that incorporate Canopy’s alternative data insights. The platform’s focus is on institutional decisioning, though consumer-facing tools may evolve as demand grows.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Filmfestivalcircuit.