Transforming Finance: The Rise of Online Account Management in Digital Banking
The shift toward online account management digital banking represents more than a convenience—it’s a fundamental redefinition of how individuals and businesses interact with their finances. Gone are the days when banking required physical branches, paper statements, and manual reconciliations. Today, a single mobile app or web portal consolidates checking accounts, investments, loans, and even cryptocurrency holdings, all accessible with biometric authentication or a few taps. This evolution isn’t just about replacing traditional methods; it’s about embedding financial intelligence into daily life, where real-time transactions, AI-driven insights, and automated savings become the norm rather than the exception.
Yet, the transition hasn’t been seamless. Early adopters faced skepticism about security, usability, and the reliability of digital-only institutions. Fraud alerts, glitchy interfaces, and occasional downtimes during critical transactions left lingering doubts. These challenges, however, accelerated innovation. Banks and fintech firms responded with multi-layered encryption, behavioral biometrics, and 24/7 customer support—transforming online account management digital banking from a risky experiment into a cornerstone of modern financial infrastructure.
The implications stretch beyond personal finance. Small businesses now leverage digital banking account management to automate payroll, track inventory-linked loans, and integrate with e-commerce platforms without intermediaries. Governments and NGOs use these systems to distribute aid, monitor fiscal transparency, and combat corruption. What began as a tool for efficiency has become a catalyst for economic inclusion, particularly in regions where physical banking infrastructure remains underdeveloped.

The Complete Overview of Online Account Management in Digital Banking
At its core, online account management digital banking refers to the suite of tools and interfaces that allow users to monitor, control, and optimize their financial assets through digital channels. This encompasses everything from viewing transaction histories and setting up direct deposits to managing investment portfolios, applying for credit, and even filing tax documents—all without stepping into a bank branch. The underlying technology combines cloud computing, application programming interfaces (APIs), and machine learning to deliver personalized, scalable, and secure financial services.The paradigm shift gained traction in the late 2000s, as smartphones and high-speed internet became ubiquitous. Traditional banks, initially resistant to digital disruption, were forced to either modernize their platforms or risk obsolescence. The rise of neobanks—fully digital financial institutions like Chime, Revolut, and N26—further democratized access, offering streamlined digital banking account management with minimal fees. Today, even legacy institutions have embraced hybrid models, where online and offline services coexist, catering to both tech-savvy millennials and older generations wary of digital adoption.
Historical Background and Evolution
The origins of online account management digital banking can be traced back to the 1980s and 1990s, when banks introduced early forms of internet banking for corporate clients. These systems were clunky, text-based, and limited to basic functions like balance inquiries and fund transfers. The turn of the millennium brought graphical interfaces and broader consumer adoption, but security remained a major hurdle. High-profile breaches in the early 2000s—such as the 2005 Heartland Payment Systems hack—eroded trust, prompting the development of stronger encryption standards like SSL/TLS and two-factor authentication.The real inflection point came with the 2008 financial crisis, when traditional banks faced scrutiny over opaque lending practices. Consumers, disillusioned by brick-and-mortar institutions, turned to digital alternatives that promised transparency and lower costs. Fintech startups capitalized on this demand, offering online account management digital banking solutions with features like instant money transfers (via services like Venmo or PayPal) and peer-to-peer lending. Regulatory sandboxes in the UK and Singapore further accelerated innovation, allowing experimental digital banks to operate under supervised conditions. By the 2010s, even central banks began exploring central bank digital currencies (CBDCs), signaling that digital banking account management was no longer a niche but a global imperative.
Core Mechanisms: How It Works
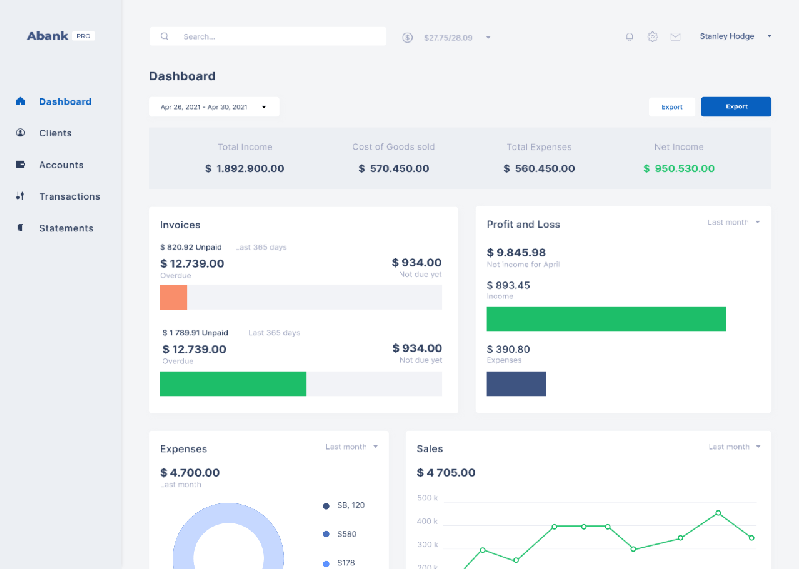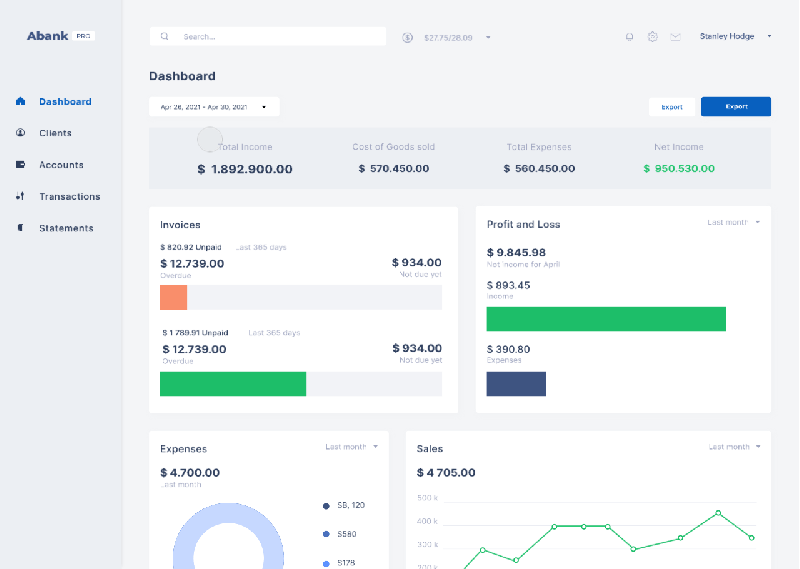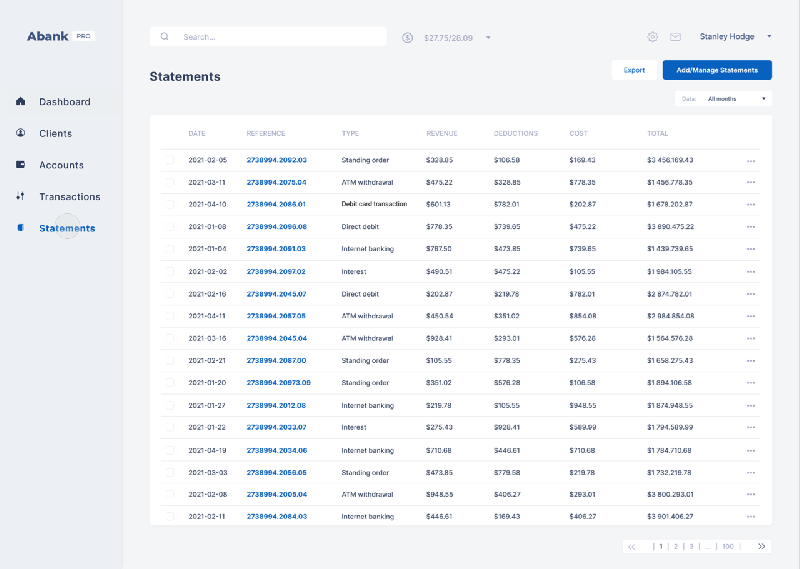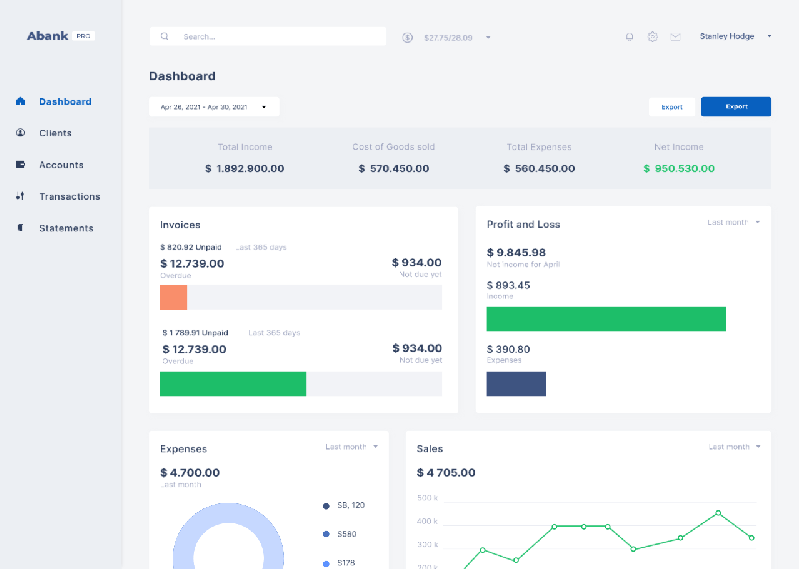
The functionality of online account management digital banking relies on three interconnected layers: the front-end user interface, the backend processing systems, and the security infrastructure. The front end—accessible via mobile apps or web browsers—provides a dashboard where users can view balances, categorize expenses, and set budget alerts. Behind the scenes, APIs connect these interfaces to core banking systems, which handle transactions, credit scoring, and compliance checks. For example, when a user requests a loan through a digital platform, the system instantly cross-references their transaction history, credit score (from bureaus like Equifax or Experian), and real-time income data to approve or deny the application within minutes.Table of Contents
- The Complete Overview of Online Account Management in Digital Banking
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Is online account management in digital banking secure?
- Q: Can I access all my financial accounts through a single digital banking portal?
- Q: What happens if my digital bank goes out of business?
- Q: How does online account management affect my credit score?
- Q: Are there any hidden fees in digital banking?
- Q: Can I use digital banking for business accounts?
- Q: How do I recover access if I lose my login credentials?
- Q: Is digital banking available in all countries?
- Q: Can I still use digital banking if I don’t have a smartphone?
- Q: How does digital banking handle tax reporting?
Security is the backbone of this ecosystem. Modern digital banking account management platforms employ a combination of static and dynamic authentication methods. Static measures include PINs, passwords, and security questions, while dynamic approaches leverage behavioral biometrics (e.g., typing speed, device location) and one-time passwords (OTPs) sent via SMS or email. Advanced systems use hardware tokens or fingerprint/Face ID verification. Additionally, banks deploy fraud detection algorithms that monitor unusual activity—such as sudden large withdrawals or logins from unfamiliar geographies—and trigger alerts or temporary account locks. The integration of blockchain technology in some platforms further enhances transparency, allowing users to audit transaction histories immutably.
Key Benefits and Crucial Impact
The adoption of online account management digital banking has redefined financial accessibility, efficiency, and user empowerment. For individuals, the benefits are immediate: 24/7 access to funds, real-time expense tracking, and automated savings tools that align with personal goals. Businesses, meanwhile, gain operational agility, with features like instant invoicing, automated receivables, and integration with accounting software like QuickBooks or Xero. Even governments have harnessed these systems to improve social welfare distribution, reducing leakage and bureaucracy. The impact extends to financial literacy; interactive dashboards and AI-driven insights help users understand spending patterns, credit health, and investment opportunities—democratizing financial knowledge that was once reserved for wealth managers.The transformation isn’t without trade-offs. While digital banking account management reduces reliance on physical infrastructure, it also introduces new vulnerabilities, such as phishing attacks or data breaches. The shift has also widened the digital divide, leaving segments of the population—particularly the elderly and those in low-income regions—without access to essential financial tools. However, the long-term trajectory is clear: the convenience, cost savings, and innovation driven by digital banking are reshaping global finance, with no sign of reversal.
"Digital banking isn’t just about moving money—it’s about moving people forward. The tools we build today will determine who gets to participate in the economy tomorrow." — Jenny Johnson, CEO of Franklin Templeton Investments
Major Advantages
- Unparalleled Convenience: Users can manage accounts, pay bills, and transfer funds anytime, anywhere, eliminating the need for branch visits or business hours. Mobile notifications for transactions or low balances ensure proactive financial oversight.
- Cost Efficiency: Digital-only banks and hybrid models reduce overhead costs (e.g., physical branches, paper statements), passing savings to customers via lower fees, higher interest rates on savings, and free ATM access.
- Enhanced Security: Advanced encryption, multi-factor authentication, and AI-driven fraud detection create a more secure environment than traditional banking, which often relies on outdated security measures.
- Financial Personalization: AI and data analytics enable tailored recommendations, such as optimized savings plans, debt repayment strategies, and investment portfolios aligned with risk tolerance.
- Global Accessibility: Cross-border transactions and multi-currency accounts (offered by platforms like Wise or Revolut) facilitate international commerce and remittances, reducing reliance on expensive wire transfers.

Comparative Analysis
While online account management digital banking offers universal benefits, the user experience varies significantly across providers. Below is a comparison of key features among leading platforms:| Feature | Traditional Banks (e.g., Chase, Bank of America) | Neobanks (e.g., Chime, N26) | Cryptocurrency Platforms (e.g., Coinbase, Binance) |
|---|---|---|---|
| Account Types | Full suite (checking, savings, loans, mortgages) | Limited (checking/savings, some credit cards) | Digital wallets, crypto trading, DeFi integration |
| Fees | Monthly maintenance, overdraft, ATM fees | Minimal/no fees (revenue from interchange) | Transaction fees, trading commissions, gas fees |
| Security | Legacy systems with gradual upgrades | End-to-end encryption, biometric auth | Private keys, cold storage, multi-sig wallets |
| User Experience | Complex, legacy UI/UX | Intuitive, mobile-first design | Highly technical, steep learning curve |
Future Trends and Innovations
The next decade of online account management digital banking will be shaped by three converging forces: artificial intelligence, decentralized finance (DeFi), and regulatory adaptation. AI will move beyond basic chatbots to offer hyper-personalized financial coaching, predicting cash flow needs and suggesting adjustments in real time. For example, a digital assistant could automatically reallocate funds from a savings account to a high-yield investment when market conditions favor it. Meanwhile, DeFi protocols will challenge traditional banking by enabling peer-to-peer lending, smart contracts for loans, and tokenized assets—though regulatory clarity remains a hurdle.Another frontier is the integration of digital banking account management with the Internet of Things (IoT). Smart home devices could auto-pay utility bills based on usage data, while wearables might trigger savings deposits when the user achieves fitness goals. Central bank digital currencies (CBDCs) will also redefine online account management digital banking, offering governments direct control over monetary policy while reducing reliance on private banks. However, interoperability between legacy systems and emerging technologies will be critical to avoid fragmentation. Banks that fail to modernize risk becoming irrelevant in a landscape where agility and innovation dictate success.
Conclusion
The rise of online account management digital banking is irreversible, but its trajectory will depend on balancing innovation with inclusivity. For consumers, the tools now available offer unprecedented control over finances, but they also demand heightened digital literacy to navigate risks like scams or misconfigured privacy settings. Businesses must adapt to meet evolving expectations, whether by adopting open banking standards or partnering with fintech firms to enhance their digital offerings. Regulators face the challenge of fostering innovation without compromising stability, particularly as cryptocurrencies and DeFi blur the lines between banking and technology.Ultimately, digital banking account management is more than a transactional convenience—it’s a reflection of how society values time, trust, and transparency. As the technology matures, the focus will shift from "can we do this digitally?" to "how can we make it better, fairer, and more human?" The banks and platforms that answer this question will not only survive but thrive in the digital-first economy.
Comprehensive FAQs
Q: Is online account management in digital banking secure?
A: Modern online account management digital banking platforms employ multiple security layers, including encryption, multi-factor authentication, and AI-driven fraud detection. However, users must also practice strong password hygiene, avoid phishing scams, and enable features like transaction alerts. While no system is 100% foolproof, reputable institutions invest heavily in cybersecurity to mitigate risks.
Q: Can I access all my financial accounts through a single digital banking portal?
A: Many digital banking account management platforms now support account aggregation, allowing you to view balances and transactions from multiple banks or credit unions in one dashboard. However, this requires consent from each institution and may not include all account types (e.g., certain investment or retirement accounts). Tools like Mint or YNAB often integrate with third-party providers to consolidate data.
Q: What happens if my digital bank goes out of business?
A: If a neobank or digital-only institution fails, deposits are typically protected up to legal limits (e.g., $250,000 per account in the U.S. under FDIC insurance for partner banks). However, some neobanks rely on partnerships with traditional banks for deposit insurance, so it’s crucial to verify coverage. Always check whether your funds are held at a FDIC-insured or equivalent institution.
Q: How does online account management affect my credit score?
A: Digital banking account management can both help and hurt your credit score. Positive impacts include on-time payments, low credit utilization (for credit cards), and access to credit-building tools like secured cards or reporting services. Negative effects may arise from missed payments, high balances, or applying for multiple credit products in a short period. Always monitor your credit report regularly via free services like Credit Karma or AnnualCreditReport.com.
Q: Are there any hidden fees in digital banking?
A: While neobanks often advertise "no fees," some online account management digital banking services may charge for overdrafts, foreign transactions, or premium features (e.g., enhanced travel insurance). Always review the terms and conditions, especially for international transfers or currency conversions, where fees can add up. Traditional banks may still have more transparent fee structures, so compare options based on your usage patterns.
Q: Can I use digital banking for business accounts?
A: Yes, many digital banking account management platforms offer business accounts with features like expense tracking, invoicing, and payroll integration. Services like Square, Stripe, or even neobanks like Brex cater specifically to small businesses, while larger enterprises may use enterprise-grade solutions like Ramp or Divvy. Ensure the platform supports your industry’s needs, such as multi-currency accounts for e-commerce or integration with accounting software.
Q: How do I recover access if I lose my login credentials?
A: Most digital banking account management systems require you to verify your identity through security questions, email/SMS codes, or government-issued ID. If locked out, contact customer support immediately—they may require additional verification (e.g., a utility bill with your address) to reset access. Never share sensitive information via unsolicited calls or emails, as these could be phishing attempts.
Q: Is digital banking available in all countries?
A: While online account management digital banking is widespread in developed economies, adoption varies globally. In regions with limited internet infrastructure or strict regulations (e.g., China’s digital yuan or India’s UPI system), local solutions may dominate. Some neobanks operate internationally, but others restrict services to specific countries. Always check the provider’s availability and compliance with local financial laws before signing up.
Q: Can I still use digital banking if I don’t have a smartphone?
A: Yes, most digital banking account management platforms offer web-based interfaces accessible via desktop or tablet. Some institutions also provide basic phone banking services or partner with third-party apps for feature phones. However, certain advanced features (e.g., biometric authentication) may require a smartphone. Always confirm the provider’s accessibility options during onboarding.
Q: How does digital banking handle tax reporting?
A: Many digital banking account management platforms generate 1099 or W-2 forms for interest, dividends, or freelance income. Some neobanks (e.g., PayPal, Venmo) may issue 1099-K forms for payment processing activities over $20,000 annually. Always review your tax documents in January and consult a tax professional if you’re unsure how transactions are categorized. Some platforms also integrate with tax software like TurboTax for seamless filing.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Filmfestivalcircuit.