How to Perfect Your Amazon Payment Online: A Definitive Mastery Guide
Amazon’s payment ecosystem is the backbone of its global retail dominance, processing billions of transactions annually with precision and efficiency. Yet, for sellers, buyers, and even casual users, navigating this system can feel like deciphering an ever-evolving financial maze. The nuances—from payment methods to fraud prevention, from seller payouts to cross-border transactions—demand a level of expertise that goes beyond basic checkout steps. Without a structured understanding, even seasoned users risk inefficiencies, security vulnerabilities, or missed optimization opportunities.
The stakes are higher than ever. With Amazon’s expansion into financial services (via Amazon Pay, Amazon Lending, and cryptocurrency experiments), the platform’s payment infrastructure has become a critical differentiator. Whether you’re a merchant looking to maximize conversions or a consumer aiming to streamline purchases, the ability to leverage Amazon’s payment systems strategically is non-negotiable. The difference between a frictionless transaction and a abandoned cart often hinges on how well you’ve mastered these mechanics.
This guide cuts through the noise to deliver actionable insights on mastering Amazon payment online comprehensively—from the technical underpinnings of Amazon’s payment gateways to advanced strategies for sellers and buyers alike. No fluff, just the essentials you need to operate at peak efficiency.

The Complete Overview of Mastering Amazon Payment Online
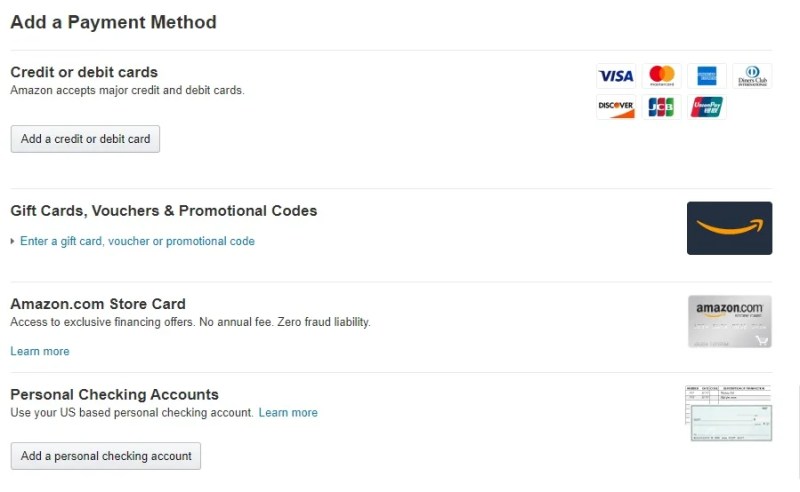
Amazon’s payment system isn’t monolithic; it’s a layered architecture designed to balance speed, security, and scalability. At its core, the system integrates multiple payment rails—credit/debit cards, digital wallets (Amazon Pay, PayPal), bank transfers, and even emerging options like Buy With Prime (which ties into Amazon’s loyalty ecosystem). For sellers, this translates to a multi-channel payout structure, where funds are distributed based on order fulfillment status, while buyers experience a seamless checkout flow optimized for repeat purchases. The platform’s ability to handle high-volume transactions with minimal latency is a testament to its infrastructure, but the real mastery lies in understanding how to interact with it—whether as a vendor managing refunds or a shopper leveraging payment plans.What sets Amazon apart is its data-driven approach to payments. The company uses machine learning to detect fraudulent activity in real time, dynamically adjusts authorization holds based on buyer history, and personalizes payment options (e.g., offering "Pay Later" to high-value customers). For businesses, this means transactions aren’t just processed—they’re analyzed for patterns that can inform inventory decisions or marketing strategies. The challenge for users is parsing through Amazon’s opaque policies (e.g., chargeback thresholds, seller account holds) to avoid costly missteps. Without this contextual knowledge, even the most straightforward payment—like a $20 purchase—can spiral into disputes or delayed payouts.
Historical Background and Evolution
Amazon’s payment ecosystem didn’t emerge overnight. It evolved alongside the company’s own retail ambitions, starting with a rudimentary checkout system in the late 1990s that relied on basic credit card processing. The real inflection point came in 2005 with the launch of Amazon Payments, a service designed to let third-party sellers (via Amazon Marketplace) accept payments without building their own infrastructure. This move democratized e-commerce for small businesses but also introduced complexity: sellers now had to navigate Amazon’s fee structures, payout schedules, and chargeback policies—all while competing with the platform’s own branded products.The next phase arrived with Amazon Pay, a standalone payment solution for non-Amazon websites, which expanded the company’s reach into B2B and B2C transactions beyond its marketplace. Then came Amazon Lending, offering sellers short-term loans backed by their future sales, further blurring the lines between retail and finance. Each iteration reinforced Amazon’s strategy: control the payment flow to retain data, reduce friction, and lock in customers. Today, the system is a hybrid of legacy banking integrations (e.g., direct ACH transfers) and cutting-edge fintech, with Amazon acting as both a merchant and a financial intermediary in many transactions.
Core Mechanisms: How It Works
Under the hood, Amazon’s payment processing pipeline is a series of interconnected steps. When a buyer initiates a purchase, the request is routed through Amazon’s Payment Services API, which authenticates the payment method, checks for fraud signals, and authorizes the transaction. For card payments, this involves a 3D Secure verification (for added security) and a real-time check against Amazon’s internal risk models. Digital wallets like Amazon Pay or PayPal are processed via their respective APIs, while bank transfers (for seller payouts) are handled through Amazon’s partnerships with financial institutions like JPMorgan Chase or Wells Fargo.Table of Contents
- The Complete Overview of Mastering Amazon Payment Online
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How does Amazon’s "Payment Hold" work, and how can sellers avoid it?
- Q: Can buyers use cryptocurrency to pay on Amazon?
- Q: What are the differences between Amazon Pay and Amazon Payments?
- Q: How do Amazon’s seller fees affect payment timing?
- Q: What should buyers do if their Amazon payment is declined?
For sellers, the process is equally meticulous. Once an order is confirmed, Amazon deducts its fees (referral fees, FBA costs, etc.) before releasing the remaining funds to the seller’s designated bank account. The timing here is critical: payouts typically occur every two weeks, but delays can happen due to account verification, chargebacks, or policy violations. The system’s transparency—or lack thereof—is often a pain point. For example, sellers may receive vague notifications about "payment holds" without clear reasons, forcing them to dig into Amazon’s Seller Central dashboard for clues. Mastering this requires familiarity with Amazon’s Payment Dashboard, where transaction histories, refunds, and fee breakdowns are logged.
Key Benefits and Crucial Impact
The efficiency of Amazon’s payment system is its most obvious advantage, but the real value lies in how it reshapes business and consumer behavior. For sellers, the ability to accept payments globally with minimal overhead reduces the friction of scaling internationally. Buyers, meanwhile, benefit from a one-click checkout experience that minimizes cart abandonment. The platform’s integration with Prime memberships further incentivizes repeat purchases, as members enjoy expedited shipping and exclusive payment perks (like early access to sales). This ecosystem effect is why Amazon’s payment volume continues to grow—it’s not just a transactional tool; it’s a growth engine.The impact extends beyond convenience. Amazon’s data-driven approach to payments allows it to offer dynamic pricing, personalized financing options, and even predictive analytics for sellers. For instance, Amazon’s Early Payments program lets sellers access up to 90% of their sales proceeds within a day (for a fee), improving cash flow. On the consumer side, tools like Amazon Pay Later (powered by Synchrony Financial) enable interest-free installment plans, making high-ticket items more accessible. These innovations aren’t just features; they’re strategic levers that deepen user engagement and loyalty.
"Amazon’s payment system isn’t just about processing money—it’s about controlling the entire customer journey. The more seamless the payment experience, the more data Amazon collects, and the harder it is for competitors to replicate." — Former Amazon Payments Executive (Anonymous)
Major Advantages
- Global Reach with Local Compliance: Amazon’s payment infrastructure handles cross-border transactions seamlessly, automatically adjusting for currency, tax laws, and local payment preferences (e.g., iDEAL in the Netherlands, Boleto Bancário in Brazil). This reduces the administrative burden on sellers operating in multiple markets.
- Fraud Mitigation: Amazon’s machine learning models flag suspicious activity in real time, reducing chargeback rates for sellers and protecting buyers from unauthorized transactions. Features like Amazon One (a palm-based payment system) add an extra layer of biometric security.
- Seller Cash Flow Optimization: Tools like Early Payments and Amazon Lending provide liquidity options that traditional banks often can’t match, helping sellers reinvest in inventory or marketing faster.
- Buyer Trust and Convenience: Amazon’s reputation for secure transactions (backed by its A-to-z Guarantee) encourages shoppers to try new payment methods, from cryptocurrency (via Amazon’s experimental pilot programs) to store credit (like Amazon.com Gift Cards).
- Data-Driven Insights: Sellers gain access to transaction analytics that reveal buying patterns, peak sales periods, and even customer lifetime value—information that can be repurposed for inventory and pricing strategies.

Comparative Analysis
| Amazon Payment System | Traditional Payment Gateways (e.g., Stripe, PayPal) |
|---|---|
|
|
Future Trends and Innovations
The next frontier for mastering Amazon payment online comprehensively lies in three areas: embedded finance, AI-driven personalization, and decentralized payment models. Amazon is already testing Amazon Cash, a digital wallet that lets users load funds via cash deposits at retail partners (a move to capture unbanked or underbanked consumers). Meanwhile, experiments with central bank digital currencies (CBDCs) and stablecoins suggest Amazon is positioning itself to be a key player in the future of global payments. For sellers, this could mean accepting crypto payments directly on Amazon Marketplace, while buyers may see more dynamic pricing tied to real-time financial data.AI will further blur the lines between payments and customer service. Imagine a system where Amazon’s algorithms not only authorize transactions but also suggest financing options or bundle products based on a buyer’s payment history. On the seller side, predictive analytics could automate refunds or dispute resolutions before they escalate. The challenge will be balancing innovation with regulatory scrutiny—especially as governments tighten oversight on big-tech financial services. One thing is certain: Amazon’s payment ecosystem will continue to evolve as a closed-loop system, where every transaction feeds back into its broader retail and financial strategies.
Conclusion
Mastering Amazon’s payment system is less about memorizing steps and more about understanding its role in the broader e-commerce ecosystem. For sellers, it’s about navigating fees, payouts, and fraud tools to maximize profitability. For buyers, it’s leveraging Amazon’s payment perks—from Prime discounts to installment plans—to stretch budgets and enhance convenience. The platform’s strength lies in its integration: payments aren’t an afterthought; they’re the engine that drives every other function, from inventory management to customer retention.The key to long-term success isn’t just keeping up with Amazon’s updates—it’s anticipating how its payment innovations will reshape commerce. Whether it’s adopting new financing tools, optimizing for Amazon’s algorithmic preferences, or simply avoiding common pitfalls (like chargeback triggers), the ability to master Amazon payment online comprehensively will remain a competitive advantage. The system is complex, but with the right strategies, it becomes a force multiplier for anyone who interacts with it.
Comprehensive FAQs
Q: How does Amazon’s "Payment Hold" work, and how can sellers avoid it?
Amazon may place a hold on seller funds for several reasons, including unresolved chargebacks, policy violations, or suspected fraud. To avoid holds, sellers should:
- Ensure all orders are fulfilled within Amazon’s timeframes.
- Monitor the "Order Defect Rate" (ODR) and keep it below 1%.
- Respond promptly to customer inquiries to prevent negative feedback.
- Use Amazon’s "Payment Dashboard" to track holds and resolve disputes proactively.
Q: Can buyers use cryptocurrency to pay on Amazon?
As of 2023, Amazon does not accept cryptocurrency as a primary payment method. However, the company has experimented with Amazon Cash (which allows crypto holders to convert digital assets to USD for purchases) and has filed patents related to blockchain-based payments. Buyers can use third-party services (like BitPay) to convert crypto to gift cards, but this is not a direct integration. For sellers, accepting crypto would require using external payment processors, which add complexity.
Q: What are the differences between Amazon Pay and Amazon Payments?
Amazon Payments is the original service that lets third-party sellers (on Amazon Marketplace) accept payments without building their own infrastructure. It’s tied to Amazon’s marketplace and handles transactions for FBA and FBM sellers.
Amazon Pay, on the other hand, is a standalone payment solution for non-Amazon websites and apps. It offers features like "Buy with Prime" and one-click checkout but operates independently of Amazon’s retail platform. Sellers using Amazon Pay benefit from Amazon’s fraud protection and global reach but must integrate it via API.
Q: How do Amazon’s seller fees affect payment timing?
Amazon deducts fees (referral fees, FBA costs, etc.) from each sale before releasing the remaining amount to the seller. For example, if a $100 sale incurs a 15% referral fee ($15) and $10 in FBA costs, the seller receives $75. Payouts are then processed bi-weekly (or via Early Payments for a fee). Delays can occur if:
- The order is returned or canceled.
- A chargeback is filed.
- The seller’s account is under review for policy compliance.
Q: What should buyers do if their Amazon payment is declined?
If a payment is declined, Amazon typically provides an error code (e.g., "513" for insufficient funds). Buyers should:
- Check their bank or card for holds or restrictions.
- Update payment methods in their Amazon account settings.
- Contact their bank to resolve any temporary blocks.
- Use Amazon’s "Saved Payment Methods" to add a backup card.
- For recurring payments (like Subscribe & Save), ensure the card has sufficient credit.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Filmfestivalcircuit.